NH Property Tax Appeal Deadlines, Step by Step
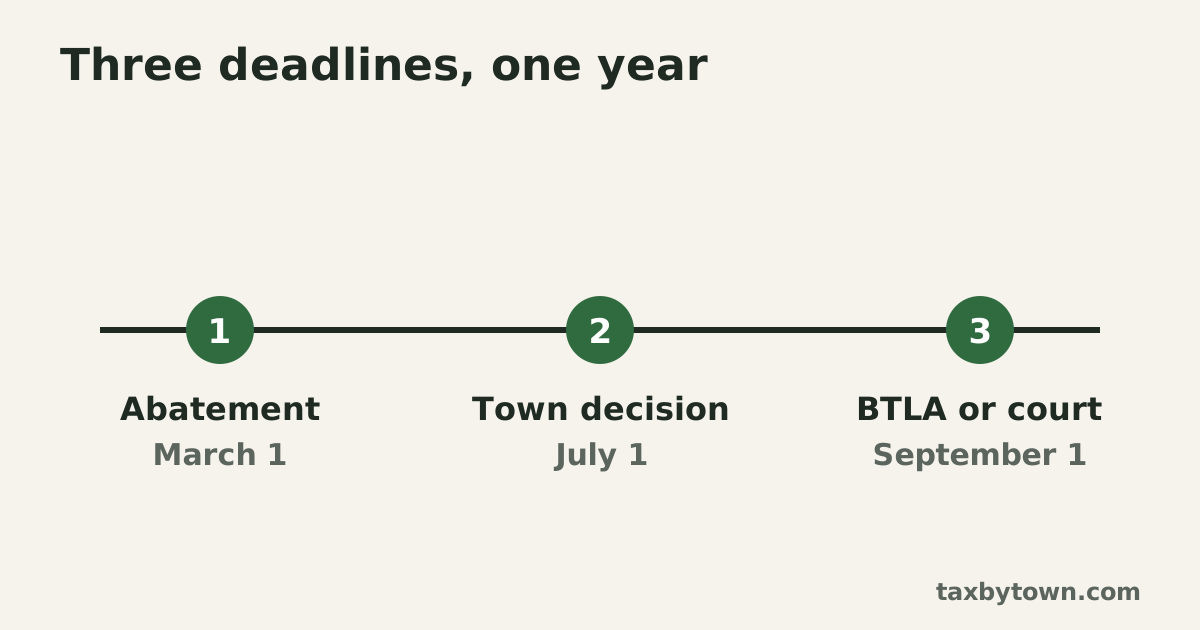
New Hampshire gives property owners one window a year to challenge an assessment, and it runs from the date of notice of tax: the day the final bill is mailed (RSA 76:1-a). Miss the first deadline and the later ones are gone too.
The three steps
| Step | Bill mailed by Dec 31 | Bill mailed after Dec 31 | Statute |
|---|---|---|---|
| Abatement application to the town or city | March 1 | 2 months after notice of tax | RSA 76:16, I(b) |
| Municipal decision | July 1 | 6 months after notice of tax | RSA 76:16, II |
| Appeal to the Board of Tax and Land Appeals, or petition to superior court | September 1 | 8 months after notice of tax | RSA 76:16-a, I; RSA 76:17 |
- Abatement application to the town or city. In writing, on the abatement form, filed with the selectmen or assessors "by March 1, following the date of notice of tax under RSA 76:1-a, and not afterwards."
- Municipal decision. The selectmen or assessors "shall grant, for good cause shown, or deny the application in writing by July 1". "The failure to respond shall constitute denial."
- Appeal to the Board of Tax and Land Appeals, or petition to superior court. "The appeal shall be filed on or before September 1 after the date of notice of tax under RSA 76:1-a, and not afterwards." The superior court route under RSA 76:17 has the same September 1 limit. A taxpayer uses one route, not both.
Worked dates
| Final 2025 bill mailed | Abatement application | Town decision | BTLA or court |
|---|---|---|---|
| December 1, 2025 | March 1, 2026 | July 1, 2026 | September 1, 2026 |
| January 15, 2026 | March 15, 2026 | July 15, 2026 | September 15, 2026 |
| February 20, 2026 | April 20, 2026 | August 20, 2026 | October 20, 2026 |
The DRA set some towns' 2025 rates in January 2026, so their final bills necessarily went out after December 31; each town page shows the date its rate was set.
Rules the Board spells out
- A Board appeal cannot be filed before the town decides or July 1 passes, and the town's silence does not extend the September 1 deadline.
- The Board and the superior court are alternatives; a taxpayer uses one.
- $65 filing fee, non-refundable, by check or money order payable to "Treasurer, State of New Hampshire"; one fee covers all lots one taxpayer owns in a town.
- Taxes keep falling due while an abatement request or appeal is pending; the town may charge interest and lien unpaid taxes.
- If the Board orders an abatement after the tax was paid, the abated amount is refunded with 6% interest.
- The taxpayer carries the burden of proving a disproportionate share of tax. An appraisal is not required; comparable sales are the usual support.
- An attorney is not required.
- The Board does not accept electronic filing.
- A building damaged by fire or natural disaster during the tax year can be prorated: apply to the town within 60 days of the event or by March 1, whichever is later (RSA 76:21).
What the Board compares, and how the equalization ratio enters, is on the appeal page and in the assessed vs market value guide.
Sources
- RSA 76:16, Abatement of Taxes by Selectmen or Assessors
- RSA 76:16-a, Appeal From Selectmen to Board of Tax and Land Appeals
- RSA 76:17, Petition to Superior Court
- BTLA, Property Tax appeals
- BTLA, Commonly Asked Questions (property tax)
- RSA 76:1-a, Notice of Tax, all read 2026-10-20.
Questions
When is the NH abatement deadline?
March 1 after the final bill, when that bill was mailed by December 31 (RSA 76:16, I(b)); otherwise 2 months after notice of tax.
When is the BTLA appeal deadline?
September 1, or 8 months after notice of tax for a late bill, and not before the town decides or July 1 passes. The filing fee is $65.